What a Wind Mitigation Inspection Is
One form, seven questions, and a stack of photographs behind every answer.
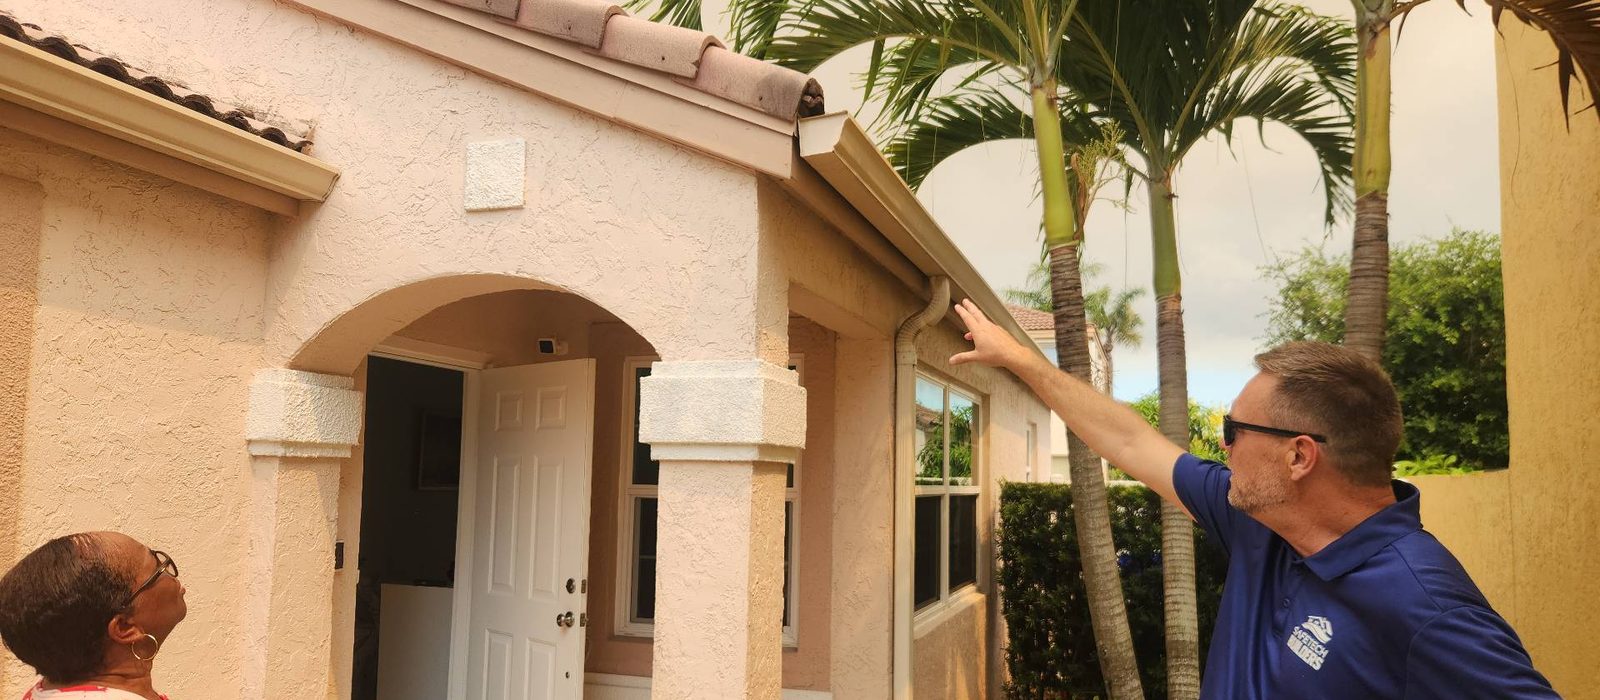
It is a visual inspection of the construction features that help a home resist hurricane winds. The inspector records findings, with photographs, on the Uniform Mitigation Verification Inspection Form (OIR-B1-1802), which your agent uses to apply the discounts and credits required under Florida Statute 627.0629.
Who can sign it. Insurers must accept forms from a licensed home inspector with approved hurricane mitigation training, a certified building code inspector, a licensed general, building or residential contractor, a professional engineer or an architect. The signer must personally inspect the home, or use a qualified direct employee where the law allows.
Insurers may verify a form independently, and knowingly submitting a false form to get a discount is a crime, so the photographs matter as much as the checkboxes.
The Seven Features on the Form
The form follows the same seven questions every time. Here is what each one asks, what scores best, and whether you can change it.
Building code, when and how the home was built
Records whether the home was built to the Florida Building Code and its permit date. Newer homes built under modern wind provisions can qualify for a building-code credit on their own, before any individual feature is counted.
Roof covering, the material and its approval
Documents the roof material, its product approval and the permit date of the installation. A permitted roof installed under current code with an approved product is the easiest to verify and score.
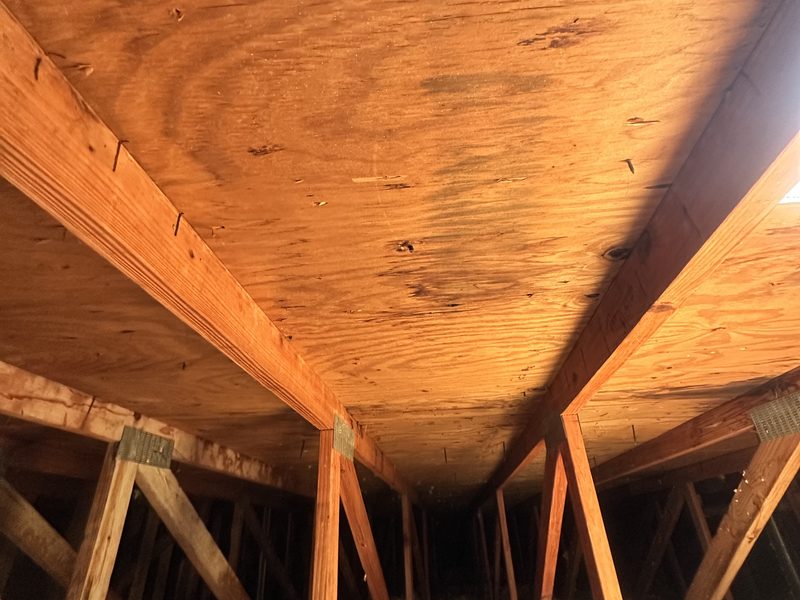
Roof deck attachment, how the plywood is held down
How the plywood or OSB deck is fastened to the trusses: nail size, type and spacing. Larger nails at tighter spacing resist uplift better and earn more credit.
Roof-to-wall connections, what ties the roof down
The hardware that ties each truss to the wall: toe-nails, clips, single wraps, double wraps or structural anchors. The inspector checks several and reports the weakest one found, so one toe-nailed addition can set the grade for the whole house.
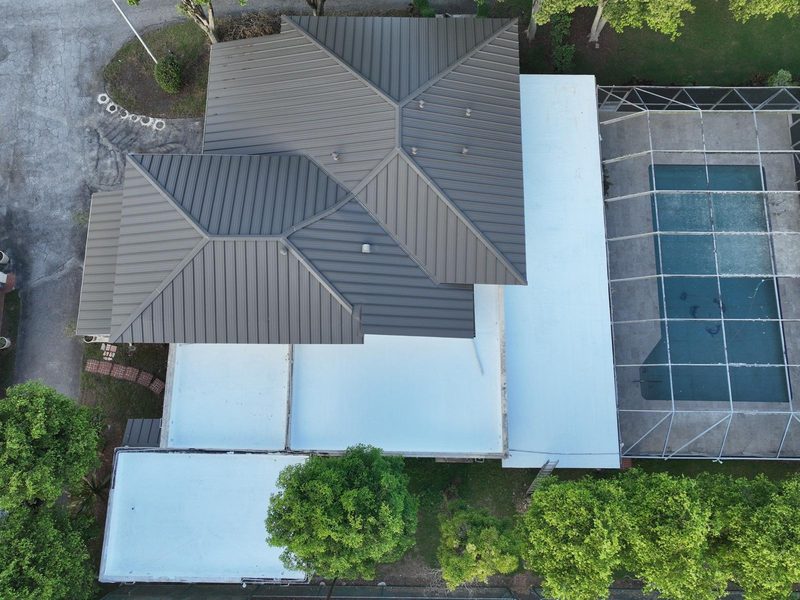
Roof geometry, the shape of the roof
Hip roofs, which slope down on all sides, handle wind better than gable roofs and often earn larger credits. Flat and mixed roofs are recorded too, by the share of roof area each covers.
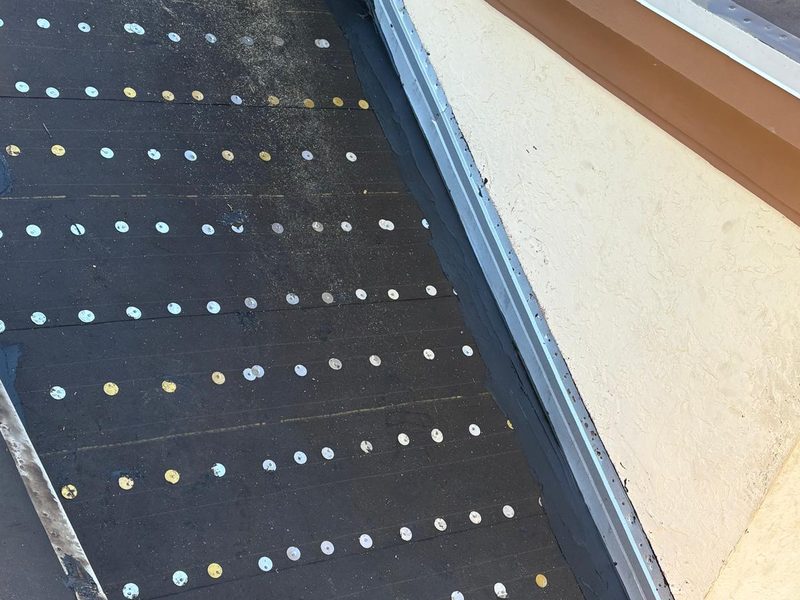
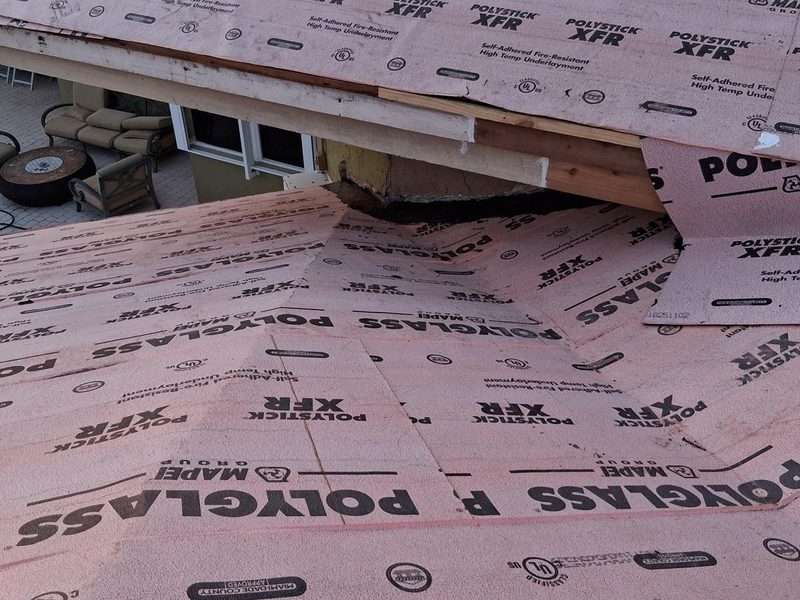
Secondary water resistance (SWR)
A self-adhering peel-and-stick layer over the deck seams or the whole deck. If wind strips the roof covering, it helps keep water out of the house, which is where most storm losses actually happen.
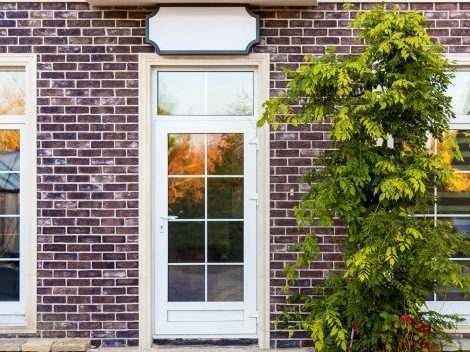
Opening protection, windows, doors and garage
Windows, entry doors, sliders, skylights and garage doors. The highest rating generally needs every opening to have approved impact protection, one unprotected opening can lower the credit for the whole house.
Tap through each feature. The stronger and better documented each one is, the more credit your insurer can apply.
How Much Can You Save?
There is no fixed number
Savings depend on your insurer's filed discounts, your home's features and your coverage. Anyone quoting a universal percentage is guessing.
Insurers publish their discounts
Florida insurers must post hurricane mitigation discount information on their websites. Your agent can price your report against it.
Undocumented means uncredited
Features that are not on the form cannot earn credit. An outdated or missing report may be costing you money.
Price the upgrade first
Before paying for a retrofit, ask your agent to price your current answer against the improved one. They can give you a real number.
How to Get Your Discount in Five Steps
Check for a report
ask your agent if one is on file and which form edition it uses.
Gather records
Permits and product approvals for roof, windows and doors.
Book an inspector
Choose one your insurer accepts, using the Rev. 04/26 form.
Send it in
ask your agent to re-rate the policy and confirm the credits.
Upgrading your roof or windows? We handle permits and closeout paperwork so the improvements are documented for your next inspection.
Wind Mitigation vs. Roof vs. 4-Point Inspection
Three inspections that sound alike and answer different questions.
Purpose: insurance discounts. Looks at the seven construction features on form OIR-B1-1802.
Purpose: repair or replacement decisions. Looks at wear, damage, leaks, flashing and remaining life, see our free roof inspection.
Purpose: insurance eligibility for older homes. Looks at roof, electrical, plumbing and HVAC condition.
Free Inspections Through My Safe Florida Home
The state's My Safe Florida Home program has offered free wind mitigation inspections and grants of up to $10,000 for eligible homeowners, toward upgrades such as roof improvements, impact windows and doors, and secondary water barriers.
availability depends on state funding and changes from year to year, so check eligibility on the program's site before planning around it. Other ways to pay for upgrades are in our roof financing guide.
Get Ready for the Inspector
Wind Mitigation FAQs
What is a wind mitigation inspection?
It is an inspection that records your home's wind-resistant features on Florida's Uniform Mitigation Verification Inspection Form (OIR-B1-1802). Insurers use the form to apply the windstorm discounts and credits Florida law requires them to offer.
Who can complete a wind mitigation inspection form in Florida?
Under Florida Statute 627.711, insurers must accept forms signed by a licensed home inspector with hurricane mitigation training, a certified building code inspector, a licensed general, building or residential contractor, a professional engineer or a professional architect. Insurers may also accept other inspectors they consider qualified. The signer must personally inspect the home or use a qualified direct employee where the law allows.
How long is a wind mitigation report valid?
Insurers commonly accept a report for up to five years if the home has not changed. Inspections done on or after april 1, 2026 must use the revised form, OIR-B1-1802 (Rev. 04/26). Re-inspect after a new roof, new impact windows or other upgrades so your discounts reflect them.
How much can a wind mitigation inspection save?
There is no fixed amount. Savings depend on your insurer's filed discounts, your home's features and your policy. Florida insurers must post their hurricane mitigation discount information on their websites, and your agent can price the discount using your report.
Is a wind mitigation inspection the same as a roof inspection?
No. A wind mitigation inspection documents construction features for insurance discounts. A roof condition inspection looks at wear, damage and remaining life to guide repair or replacement. Many homeowners need both, especially with an older roof.
Can a new roof improve my wind mitigation report?
Often, yes. A permitted re-roof can document current roof covering approvals and deck attachment, and may add a secondary water barrier. Ask for a new inspection after the final permit inspection so the improvements are recorded.
Can I get a free wind mitigation inspection?
Possibly. The state's My Safe Florida Home program has offered free wind mitigation inspections and grants for eligible homeowners when funding is available. Check current eligibility and availability on the program's website.
How We Can Help
Roof Inspection
A written condition report with photos, the starting point for any upgrade plan.
Roof Replacement
approved covering, re-nailed deck and secondary water barrier, permitted and inspected.
Hurricane Impact Windows
Impact-rated windows for every opening on the form.
Impact Doors
Entry and sliding doors with approved impact ratings.
Where We Do This Work
SafeTech Roofing and Windows installs roofs, impact windows and impact doors across Broward, Miami-Dade and Palm Beach counties.

Written by Roshy Rajan
Founder, SafeTech Roofing and Windows
Roshy Rajan has worked in Broward County real estate and construction since 2006. He founded SafeTech Roofing and Windows (SafeTech Builders Inc.) after a hurricane left a friend with roof and window damage and the referrals kept coming. Florida Certified General Contractor CGC1537934 · Certified Roofing Contractor CCC1336954 · BBB Accredited. Read his story →
Sources
- Florida Statute 627.0629, windstorm mitigation discounts
- Florida Statute 627.711, uniform mitigation verification form
- Uniform Mitigation Verification Inspection Form changes (Citizens)
- My Safe Florida Home program
This article is general education, not insurance or legal advice. Discounts, form acceptance and program availability vary, confirm with your insurer or agent.