Newly installed dark architectural shingle roof with a hip section on a South Florida home at sunset
Roofing Tips · Florida 25% Rule

Roof Repair vs. Replacement: How to Decide

In South Florida the decision is not only about the damage. It is about when the roof was installed, how much of it the repair touches, what your policy covers, and how many years the roof has left. Get those four facts and the answer usually makes itself.

Below: a side-by-side checklist, Florida's 25% rule and its 2007-code exception, what insurance does and doesn't cover, and the upgrades a replacement brings.

★★★★★ 5.0 Google Reviews10-Year Workmanship Warranty on ReplacementsLicensed & Fully Insured
◆
25% rule baseline
2007 FBC
◆
Law & ordinance default
25% of Dwelling
◆
Insurer roof-age line
15 Years
◆
Replacement warranty
10-Yr Workmanship

Repair or Replace: The Checklist

Score your roof on these seven lines. Mostly left column: repair. Mostly right: replacement is usually the better value.

FactorLeans repairLeans replace
Extent of damageOne area or one slopeSeveral areas, or spread across the roof
Roof agePlenty of life left for its typeNear or past its typical lifespan
Install codeBuilt or replaced under the 2007 code or laterInstalled before the 2007 code
Repair scopeWell under a quarter of the roof or sectionat or over 25% within 12 months
Leak historyFirst leak, clear causeSame areas leaking again after patches
Underlayment (tile)Sound under the damaged tilesBrittle or cracked across the roof
InsuranceNo renewal concernsInsurer flagging roof age or condition

Typical lifespans: 15–25 years for shingle, 40–50+ for tile, 40–70 for metal. See how long roofs last in Florida.

Florida's 25% Rule, Explained

The single biggest Florida-specific factor, and the most misunderstood.

The Florida Building Code limits how much of a roof or roof section can be repaired, replaced or recovered in any 12-month period before the whole roof or section must be brought up to current code. That is the "25% rule".

Since 2022, Florida Statute 553.844(5) adds an exception: if the roof or section was built, repaired or replaced under the 2007 Florida Building Code or later, only the repaired portion must meet current code, even when 25% or more is being repaired.

So the first question is not "how much is damaged?" It is "when was this roof permitted?" Your permit history answers it. Full detail: Florida's 25% roof rule explained.

When Each One Makes Sense

Repair makes sense when…

The damage is contained

  • Damage is isolated to one area
  • The roof is relatively new, or built under the 2007+ code
  • The repair stays well inside code limits
  • Underlayment around the damage is sound
  • Matching tiles or shingles are available
Replacement is better when…

The roof is the problem

  • Damage is widespread or on several slopes
  • The roof is near the end of its service life
  • The repair scope triggers a code upgrade anyway
  • Leaks return after patching
  • Your insurer is flagging roof age or condition
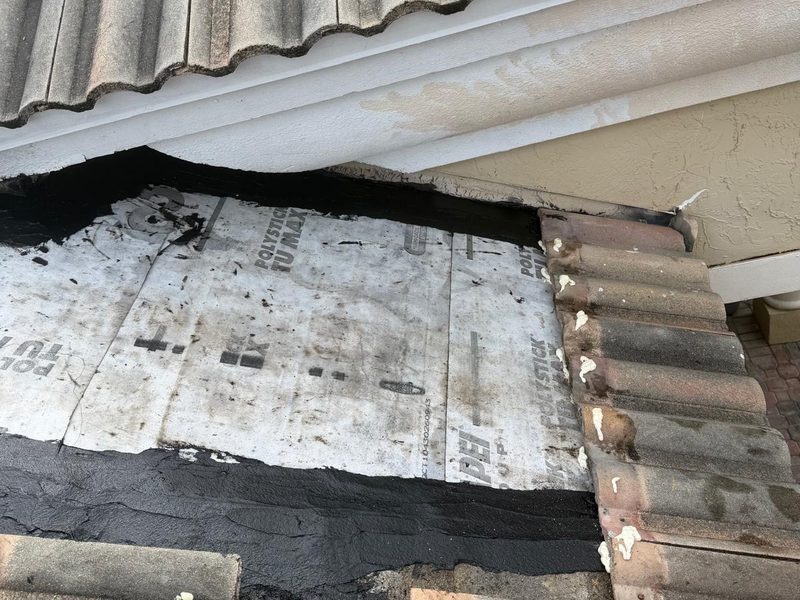
New self-adhered underlayment installed at a roof-to-wall section with surrounding tiles removed
A proper repair: tiles off, new self-adhered underlayment down, flashing sealed at the wall.
SafeTech crew replacing worn roof decking with new plywood during a South Florida roof replacement
A replacement: old roof off, damaged decking replaced and re-nailed before anything new goes down.

Not sure which column you're in? We'll price both options so you can compare them side by side.

What Insurance Does, and Doesn't, Do

Your policy decides coverage. These Florida rules decide how it is applied.

Covered perils

Sudden damage from a covered peril, hurricane, wind, hail, a falling tree, may be paid, subject to your deductible, exclusions and limits. Age, wear and poor maintenance usually are not covered.

Repair, not replace

Florida law preserves an insurer's right to repair damaged property where the policy allows it. A covered loss does not automatically mean a new roof.

Law and ordinance

Under Florida Statute 627.7011, policies include law and ordinance coverage of 25% of the dwelling limit unless you rejected it in writing; insurers must offer 50%. It pays code-upgrade costs, generally for the damaged portion unless total damage exceeds 50% of replacement cost.

Roof deductibles

Some Florida policies carry a separate roof deductible under s. 627.701(10). Check your declarations page before you assume what you'll pay.

Roof age

Insurers can't refuse to renew solely because a roof under 15 years old is old; older roofs get an inspection option. See roof insurance non-renewal.

What a Replacement Brings

A repair restores. A replacement resets the clock, and brings the roof up to today's code.

Secondary water barrier

Self-adhered underlayment that keeps water out if the covering is stripped, and a line on the wind mitigation form.

Deck re-nailing

The deck is re-fastened to current code, often required during a re-roof, see deck re-nailing in Broward.

Roof-to-wall connections

Florida's existing-building provisions can require roof-to-wall connections to be evaluated and improved at re-roof, with the mandatory share capped as part of the roof cost. Your permit and inspection confirm what applies.

approved products

Coverings approved for High-Velocity Hurricane Zone use in Broward and Miami-Dade, see HVHZ requirements.

Permit and records

A permitted, inspected roof with a clean start date for insurance and resale, and a fresh wind mitigation report.

Cost Over Time

Price the remaining life

Compare a repair against the years it actually buys, not against the full replacement price.

Watch the repeat bill

Two or three repairs on an aging roof can approach the cost of starting over, with leak damage in between.

Spread the cost

In-house financing, with every term in writing, see roof financing.

How We Decide With You

The same four steps every time, and the questions worth asking any roofer.

Step 1

Inspect

Photos of every slope, the flashing and, on tile, the underlayment.

Step 2

Check the history

Permit dates tell us which code applies and how the 25% rule works on your roof.

Step 3

Price both

an itemized repair scope and a replacement estimate, side by side.

Step 4

Your call

A written recommendation, then permitted, inspected work if you go ahead.

→ask when the roof was last permitted
→ask how much of the roof or section the repair touches
→ask for photos of the damage, not just a description
→ask whether the repair needs a permit
→ask what warranty each option carries
→ask for both prices in writing
→Verify the license at MyFloridaLicense.com
→Never sign under pressure on the day of the visit

Repair vs. Replacement FAQs

How do I know whether to repair or replace my roof?

Repair when damage is limited to one area, the roof has years of life left and the work stays within code limits. Replace when damage is widespread, leaks keep returning, the underlayment under tile is worn out, or the roof is near the end of its typical lifespan. A written inspection with photos is the reliable way to decide.

What is Florida's 25% roof rule?

The Florida Building Code limits how much of a roof or roof section can be repaired, replaced or recovered in a 12-month period before the whole roof or section must be brought up to current code. Under Florida Statute 553.844(5), if the roof or section was built, repaired or replaced under the 2007 Florida Building Code or later, only the repaired portion must meet current code, even when 25% or more is repaired.

How do I know if my roof was built under the 2007 code or later?

Check the permit history for your property. The date of the last full roof permit and its final inspection tells you which code applied. Your city or county permit portal, or your roofing contractor, can look it up.

Will insurance pay to replace my roof instead of repairing it?

It depends on the cause, the extent of damage and your policy. Sudden damage from a covered peril may be paid, minus your deductible; age and wear usually are not. Florida law also allows insurers to repair damaged property where the policy gives them that right, so a covered loss does not automatically mean a new roof.

What is law and ordinance coverage?

It pays the extra cost of bringing repairs up to current building code. Under Florida Statute 627.7011, homeowners policies include law and ordinance coverage of 25% of the dwelling limit unless you rejected it in writing, and insurers must offer 50%. It generally applies to the damaged portion unless total damage exceeds 50% of the replacement cost.

Is a roof replacement more expensive than repeated repairs?

Upfront, yes. Over time, repeated repairs on a roof near the end of its life often cost more in total, and leaks can damage the decking and interior in between. Compare the repair cost against the remaining life of the roof, not just against the replacement price.

Do roof repairs need a permit in Florida?

Many do. Re-roofing and most repairs beyond minor maintenance require a permit and inspection, and in Broward and Miami-Dade the work must meet High-Velocity Hurricane Zone requirements. A licensed contractor knows which jobs need one and pulls it.
How We Can Help

Where We Do This Work

SafeTech Roofing and Windows repairs and replaces roofs across Broward, Miami-Dade and Palm Beach counties.

Roshy Rajan, founder of SafeTech Roofing and Windows

Written by Roshy Rajan

Founder, SafeTech Roofing and Windows

Roshy Rajan has worked in Broward County real estate and construction since 2006. He founded SafeTech Roofing and Windows (SafeTech Builders Inc.) after a hurricane left a friend with roof and window damage and the referrals kept coming. Florida Certified General Contractor CGC1537934 · Certified Roofing Contractor CCC1336954 · BBB Accredited. Read his story →

Sources

This article is general education, not legal or insurance advice. Your roof's condition, permit history, policy and local code decide the right option, confirm with a licensed contractor, your insurer or an attorney.

Repair or replace? Get it in writing

One visit gives you photographs, the roof's permit history, an honest remaining-life estimate and itemized prices for both options, free, with no pressure either way.


Repair or replace? Free inspection with a written recommendation and both prices.
Call (954) 665-3231 Free Estimate